The UK ramps up enforcement against unregistered peer-to-peer crypto trading, signaling a shift towards stricter regulation as new legal frameworks emerge.
Heightened Regulatory Focus in the UK
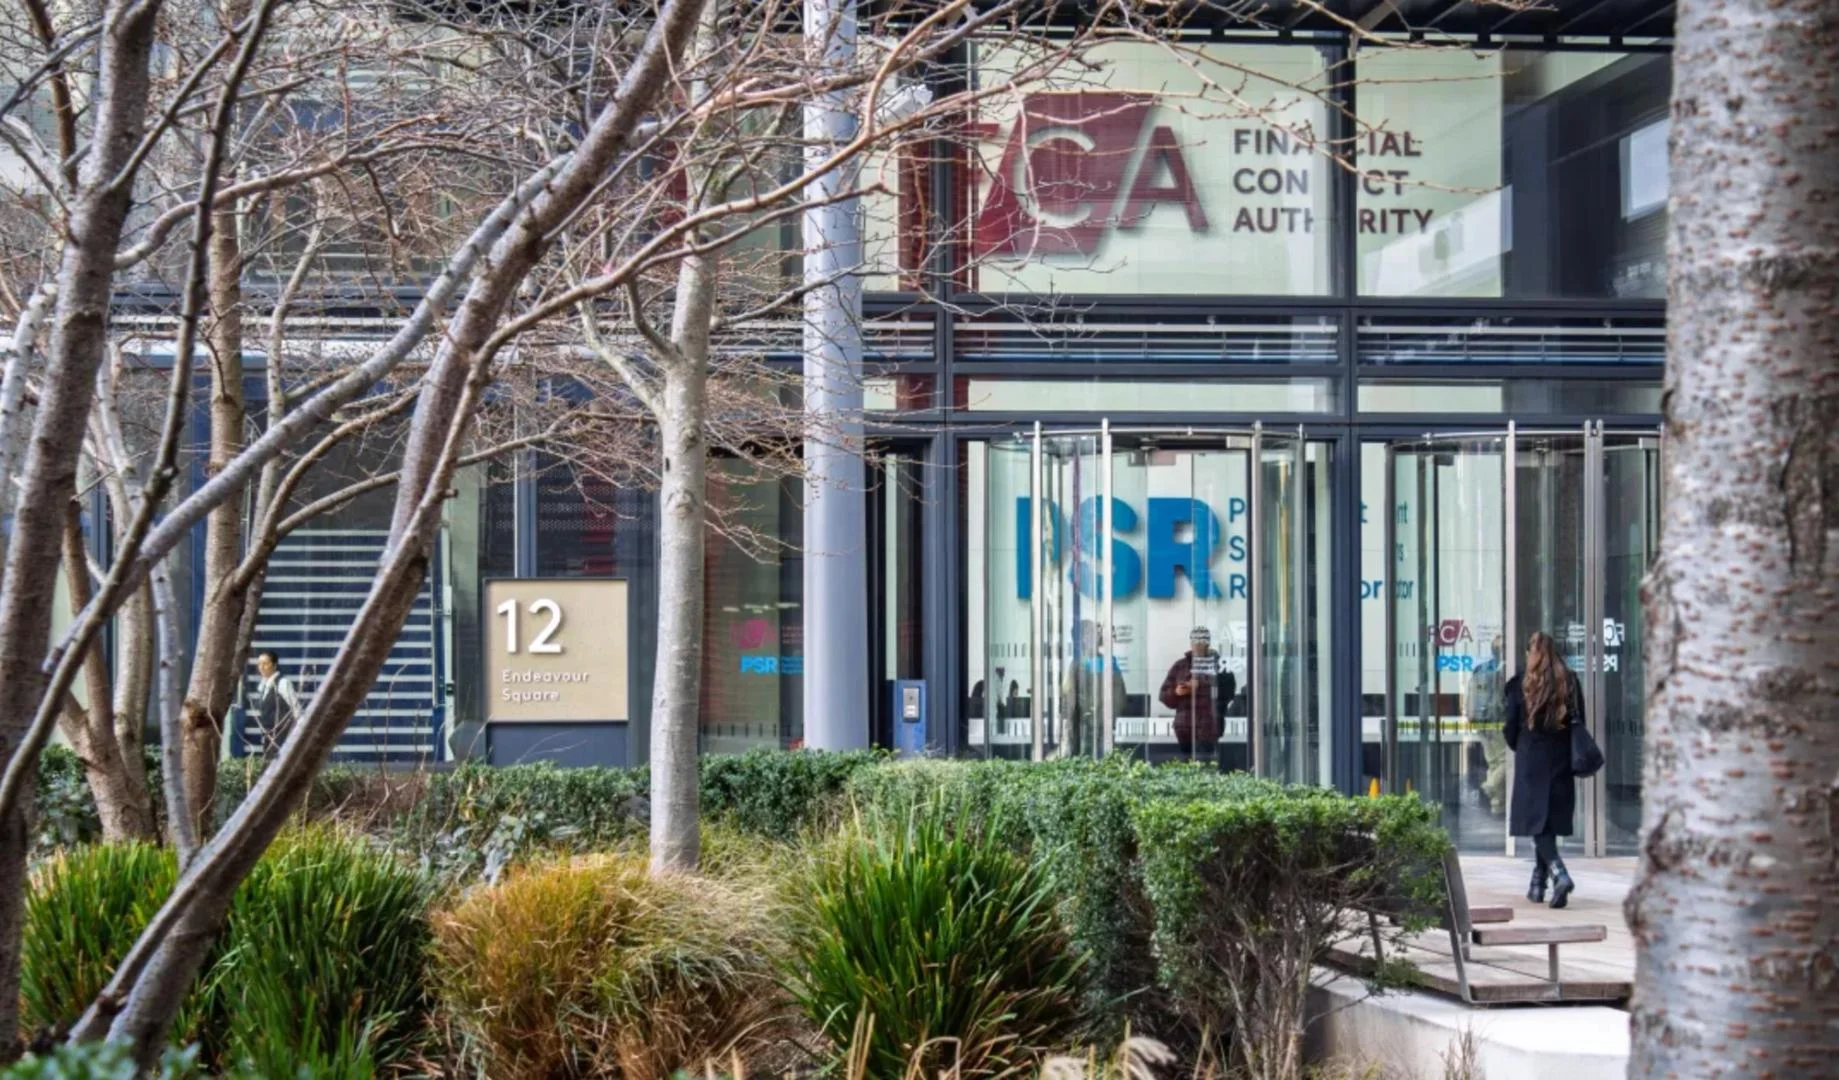
The UK's Financial Conduct Authority (FCA) has intensified its scrutiny of unregulated peer-to-peer cryptocurrency transactions. Recently, the FCA executed a coordinated enforcement initiative in London, targeting operations that allegedly engage in illegal crypto trading. This initiative illustrates a growing commitment from the FCA to address the unregulated aspects of the cryptocurrency market, an area that has long been a concern for regulators globally.
This crackdown combined efforts from not just the FCA but also HM Revenue & Customs (HMRC) and London's Metropolitan Police. This kind of joint operation isn't merely procedural; it suggests a unified stance among various regulatory bodies on the need to crack down on unlawful activities within the crypto realm. Cease-and-desist orders were issued to three venues suspected of facilitating these transactions. This raises serious questions about the overall legitimacy of peer-to-peer trading platforms operating in the UK.
The Status of Cryptocurrency Regulation in the UK
Currently, no peer-to-peer crypto businesses are registered with the FCA in the UK. This situation underscores the significant regulatory gap that exists in a marketplace that's rapidly evolving. The FCA's position is clear: these operations are skirting essential measures designed to combat money laundering and protect consumers from potential fraud and abuse. As the market continues to grow, the lack of regulation is increasingly seen as an open invitation for criminal activity.
Caroline Black, a consultant at Gherson Solicitors LLP, points out that this operation marks a pivotal shift. The FCA is moving from simply issuing warnings to taking direct action against unregistered crypto trading activities. This is more significant than it looks. It suggests that the regulators are serious about pushing the industry into compliance. Black notes that criminal liability now poses a real threat for any operator engaging in business without proper registration. This could serve as a wake-up call for those thinking they can operate under the radar.
Changing Landscape of Regulatory Obligations
Aditya Mittal, managing principal at Capco, stresses the importance for firms to understand their regulatory obligations in light of the FCA's recent guidance. This guidance clarifies the framework for the UK's forthcoming cryptoasset regulations, set to take full effect by October 2027. What this means for you, if you're working in this space, is that compliance isn't just a checkbox exercise; it’s imperative for survival. The looming deadline emphasizes that businesses need to have their ducks in a row as the clock ticks down to the registration deadline.
Firms engaging in activities like issuing qualifying stablecoins, running crypto exchanges, coordinating crypto deals, and safeguarding digital assets must seek FCA approval. The application window closes on February 28, 2027. With this increasing regulatory pressure, the UK's approach appears to be shifting significantly from a previously permissive stance to a more stringent regulatory culture. This might be alarming for some entrepreneurs, but it could also provide a more structured environment for those compliant with guidelines.
Implications for the Cryptocurrency Market
This heightened regulatory scrutiny doesn’t happen in isolation. It reflects global trends where jurisdictions are trying to strike a balance between encouraging innovation in financial technologies and implementing necessary consumer protections. Countries around the world are wrestling with how best to address the complexities of digital currencies and assets while ensuring that consumers are safeguarded against possible losses and fraud.
The tightening regulations in the UK may be interpreted as a warning shot to other jurisdictions lagging in regulatory oversight. If local businesses are unable or unwilling to navigate these emerging frameworks, they risk facing significant penalties and possibly losing their market position. This is particularly troubling for smaller firms that often operate on thin margins and have less capacity to absorb regulatory costs.
This crackdown is, of course, part of a broader dialogue about the future of cryptocurrencies. As traditional financial institutions begin to incorporate blockchain technologies, the clash of traditional finance with emerging digital assets becomes increasingly significant. Operators in the crypto space need to be aware not just of local regulations but of how these regulations might ripple across borders, particularly as collaborative enforcement becomes more common.
And yet, one has to question: will these measures genuinely address the issue of illicit trading in cryptocurrencies, or merely push it further underground? This is the part most people overlook. The reality is that while regulations can tighten legal frameworks, laws alone won't eliminate illegal activity. Operators need to embrace compliance not just to avoid penalties but to foster trust and legitimacy in an industry still grappling with its reputation.
In essence, the UK's approach to regulating cryptocurrency is evolving rapidly, and those in the sector must adapt or face the consequences. The stakes are higher than ever.



Discussion
Sign in to join the discussion.